Sinopharm Group (HKEX: 1099) | Evaluating the Discount — October 2026

All the numbers presented in the article are taken directly from our dashboards.
Sinopharm Group Co. Ltd. (HKEX: 1099) is a prominent player in the People’s Republic of China’s healthcare market, specializing in the wholesale and retail of pharmaceuticals, medical devices, and related health products.
The company’s operations are organized into four main divisions.
Pharmaceutical Distribution
Supplies pharmaceutical goods to hospitals, fellow distributors, retail pharmacies, and clinics. Additionally offers extensive distribution, logistics, and value-added support to both domestic and international manufacturers and suppliers in the pharmaceutical and healthcare sectors.
Medical Devices
Solely focused on the distribution of various medical equipment.
Retail Pharmacy
Manages and franchises a vast chain of drug stores.
Other Business
A segment involved in the manufacturing and sale of pharmaceutical products, chemical reagents, and laboratory supplies.
Beyond these core areas, the company also engages in property rental and management, further distributes specialized items such as medical instruments, traditional Chinese herbal medicines, antibiotics, and biological products.
Sinopharm also provides a comprehensive list of services; IT development, medicine and health consultations, investment services, import/export facilitation for goods and technology, various business and market information consulting, and the organization of conventions and exhibitions. Moreover, it oversees medical project investments, offers related consulting, and provides technological training.
Operations
Full-Year 2025
Revenue -1.6% YoY.
Net profit +3.94% YoY.
Pharmaceutical distribution revenue -2.02% YoY.
Medical device distribution revenue -2.02% YoY.
Retail pharmacy revenue +6.67% YoY.
Overall expense ratio -0.25% YoY.
Reported its annual revenue growth rate exceeding the overall industry level and that its market share continued to increase.
Retail pharmacy segment achieved a strategic turnaround in terms of loss reduction.
H1 2026
Revenue -1.13% YoY.
Net profit -2.95% YoY.
Pharmaceutical distribution revenue -1.39% YoY.
Medical device distribution revenue -0.35% YoY.
Retail pharmacy revenue +8.58% YoY.
Added 35 new SPD (Supply-Processing-Distribution) projects and 28 single-hospital centralized distribution projects in the medical device intelligent supply chain.
In August 2026, Sinopharm Group Co. Ltd., together with its subsidiary China National Medicines Corporation Ltd and its ultimate controlling shareholder China National Pharmaceutical Group Co., Ltd., entered into an equity transfer agreement with Shanghai Shyndec Pharmaceutical Co., Ltd. Under the agreement, the three sellers disposed of a combined 51% equity interest in China National Medicines Guorui Pharmaceutical Co., Ltd. for a total consideration of RMB 406.3634M.
Upon completion, Guorui Pharmaceutical ceased to be a consolidated subsidiary of Sinopharm Group, with the company no longer holding any direct equity interest in the company, with its remaining indirect interest held solely through China National Medicines Corporation at 49%.
Valuation
Key Takeaways
The company maintains a conservative ~30% earnings payout ratio and a reliable ~5% in dividends at current levels. ✔️
As a state-owned enterprise controlling China's densest medical logistics network, its massive revenue scale provides long-term terminal value security. ✔️
Shares trade at a P/E ratio of ~6x and as well as a meaningful discount to Book Value (P/B). ✔️
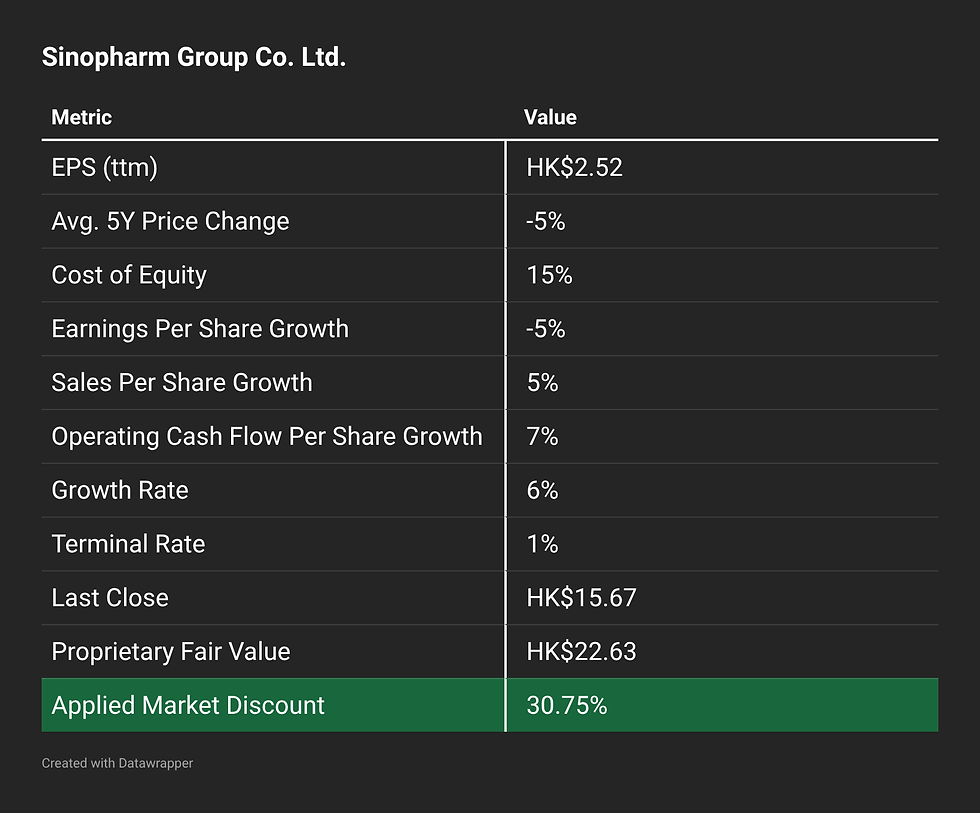
As it currently stands, the company stock is trading at a 30.75% discount to our proprietary estimate.
Risks
Low-margin, high volume type of business. ❌
Margins face ongoing downward pressure due to regulatory changes in China, specifically the expansion of Volume-Based Procurement (VBP) and strict drug price directives. ❌
Being an established corporate giant, earnings momentum has slowed down (leading to our modest 6% growth rate expectation). ❌
Sustained Performance & Conclusion ⚠️
Variables include:
Continued maintenance of cost. ⚠️
Growth in the retail pharmacy network. ⚠️
Monitoring of their payout ratio to protect their dividend yield. ⚠️
Optimizing their collection cycles to maintain their Interest Coverage Ratio, ensuring their thin margins are not squeezed by rising debt costs. ⚠️
Though near-term earnings momentum remains low, the stock's deep discount to both book value offers a considerate margin of safety. As outlined above, the trajectory of the higher-margin retail pharmacy segment—and management's ability to maintain an attractive dividend payout—will be critical in offsetting ongoing pricing pressures from VBP.
With China’s leading medical logistics provider, the security provided by its state-owned scale and reliable dividend yield will likely outweigh the current concerns of a low-margin operating environment.
Best regards,
- The Intrival Team


